What a typical "mortgage insurance package" includes
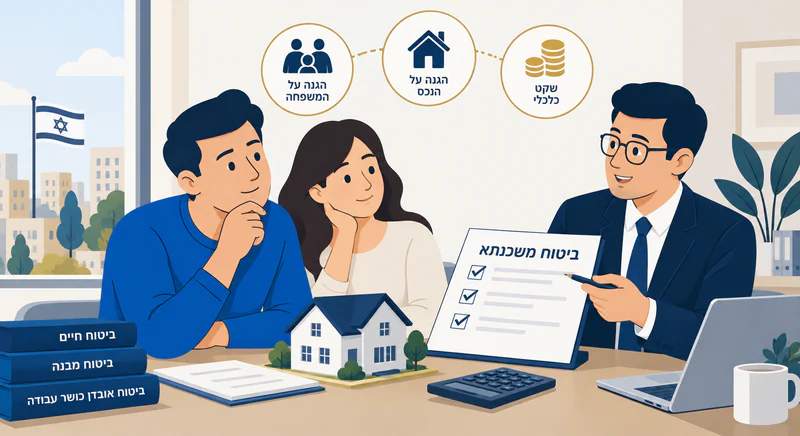
In most cases the package includes two main policies: a decreasing-term life policy designed to settle the remaining mortgage balance if the insured passes away during the term, and a building insurance policy designed to protect the mortgaged property against physical damage. The exact terms — exclusions, waiting periods and benefit caps — are defined by the specific policy.
The bank registers a lien on the property and also requires beneficiary instructions for paying the insurance proceeds in line with the loan terms. Additional coverage such as private life insurance, disability insurance or full home-contents insurance is not an automatic part of "mortgage insurance" and should be considered separately.
What the bank may require and what is not automatic
Banks typically require two components: a life policy on the borrowers in the loan amount and for the loan term, and a building policy for the mortgaged property. Specific requirements (sums, beneficiaries, powers of attorney, annual renewal) depend on the loan terms and on the bank's documents.
- Life cover in the loan amount and for the repayment period — usually a decreasing-term policy.
- Building insurance for the mortgaged property, with the bank as beneficiary per the loan terms.
- Powers of attorney to renew the policy and exchange information between the bank and the insurer.
- Proof that the policy is in force at every annual renewal.
Private life insurance, disability cover and home-contents insurance are a separate decision. They are not an automatic bank requirement.
Mortgage life insurance vs. private life insurance
Mortgage life insurance is a dedicated policy whose sum insured decreases over time in line with the loan repayment schedule, which keeps the premium relatively low. The benefit may be paid directly to the bank as beneficiary to clear the remaining mortgage, subject to the policy terms.
- Mortgage life insurance: decreasing sum, beneficiary tied to the bank, relatively low premium.
- Private life insurance: fixed or dynamic sum, the insured / family as beneficiary, broader family protection.
- In most cases the two products complement each other rather than replace each other.
- Always review existing life coverage inside pension funds and managers' insurance before deciding.
Building insurance for mortgage — what's in and what's out
Building insurance attaches to the mortgaged property and typically covers physical damage to the structure, such as fire, water-pipe damage, natural-disaster damage and earthquake where included, sometimes as a separate cover. It does not cover home contents, does not cover items outside the building structure, and is not a substitute for a full home insurance policy covering contents and liability.
Buying through the bank vs. through an independent agent / insurer
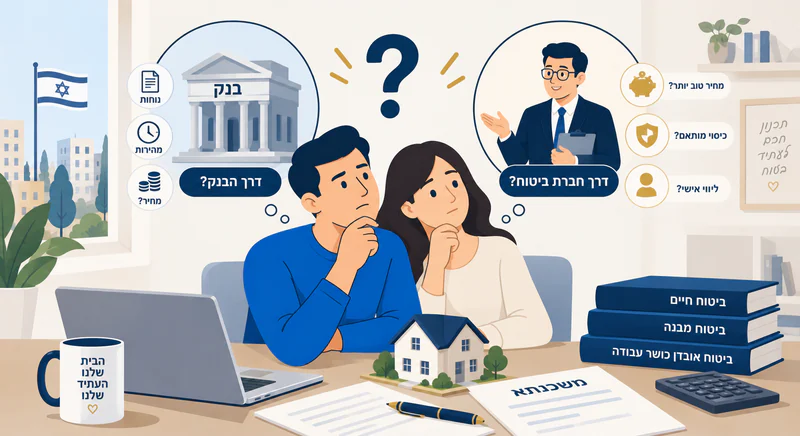
The Israeli insurance and banking regulators have published guidance treating mortgage insurance as a transaction separate from the loan itself. In practice: the insurance can be bought through the bank or from an independent insurer, and it is reasonable to compare offers before signing.
| Topic | Through the bank | Through an independent agent / insurer |
|---|---|---|
| Choice of insurer | The bank presents one or a few policies it distributes. | Quotes from multiple insurers; you choose on terms and price. |
| Comparison process | Narrower comparison inside the bank channel. | Structured multi-insurer comparison before signing. |
| Claims support | Bank or insurer call centre via the bank. | Personal claims support from the agent. |
| Personalization | Standard policy tied to the loan terms. | Tailoring for age, family status and joint borrowers. |
| Replacing the cover later | Subject to the policy terms and coordination with the bank. | Subject to the policy terms and coordination with the bank. |
Any comparison still depends on the specific policy terms and on the bank's requirements. It is worth getting at least two quotes before signing.
How to replace an existing mortgage insurance policy
The policies can be replaced, subject to the terms of the existing policy and the bank's requirements. The general steps are:
- 1Get a competitive quote from another insurer and read the new policy terms carefully.
- 2Request a waiver letter or bank approval to transfer the coverage to the new policy.
- 3Time the start of the new policy and the end of the old one to avoid any coverage gap.
- 4Update beneficiaries, powers of attorney and bank details on the new policy.
- 5Keep the supporting documents and file them with the bank's mortgage file.
Switching does not guarantee a saving. Compare not only the premium but also exclusions, benefit caps, annual renewal and claims support.
Documents typically required
- ID documents for the borrowers and an up-to-date health declaration.
- Loan details: amount, interest rate, term and amortization schedule.
- Property details: address, block/parcel, size, intended use.
- Evidence of existing life cover inside pension and managers' insurance (helps right-size the new life policy).
- Records of past claims or material medical conditions, where relevant.
Common mistakes before signing
Signing the bank's policy quickly without comparing.
You can request time to review a policy from an agent or another insurer. The insurance is a transaction separate from the loan.
Relying on mortgage life insurance alone.
Mortgage life insurance settles the remaining loan but usually leaves no additional sum for the family. Top-up cover should be reviewed separately.
Accepting health exclusions without checking alternatives.
Another insurer may accept the application on different terms. It is worth approaching an independent agent before giving up coverage.
Forgetting the annual renewal of the building policy.
The bank relies on the policy being in force. Keep proof of renewal both in your personal file and in the bank's file.
Confusing building insurance with full home insurance.
Mortgage building insurance usually excludes home contents and liability. Home-contents cover is bought separately.